Seven associations representing European universities and research institutions (CESAER, the Coimbra Group, EU-LIFE, the EUA, The Guild, LERU, YERUN) issued a joint statement on 9 September 2026 calling for the budget of the 10th Framework Programme to be increased to at least €200 billion in order to ensure the stable and predictable development of European competitiveness, prosperity and security. In this context, they regard expenditure on research, development and innovation as a key strategic investment.
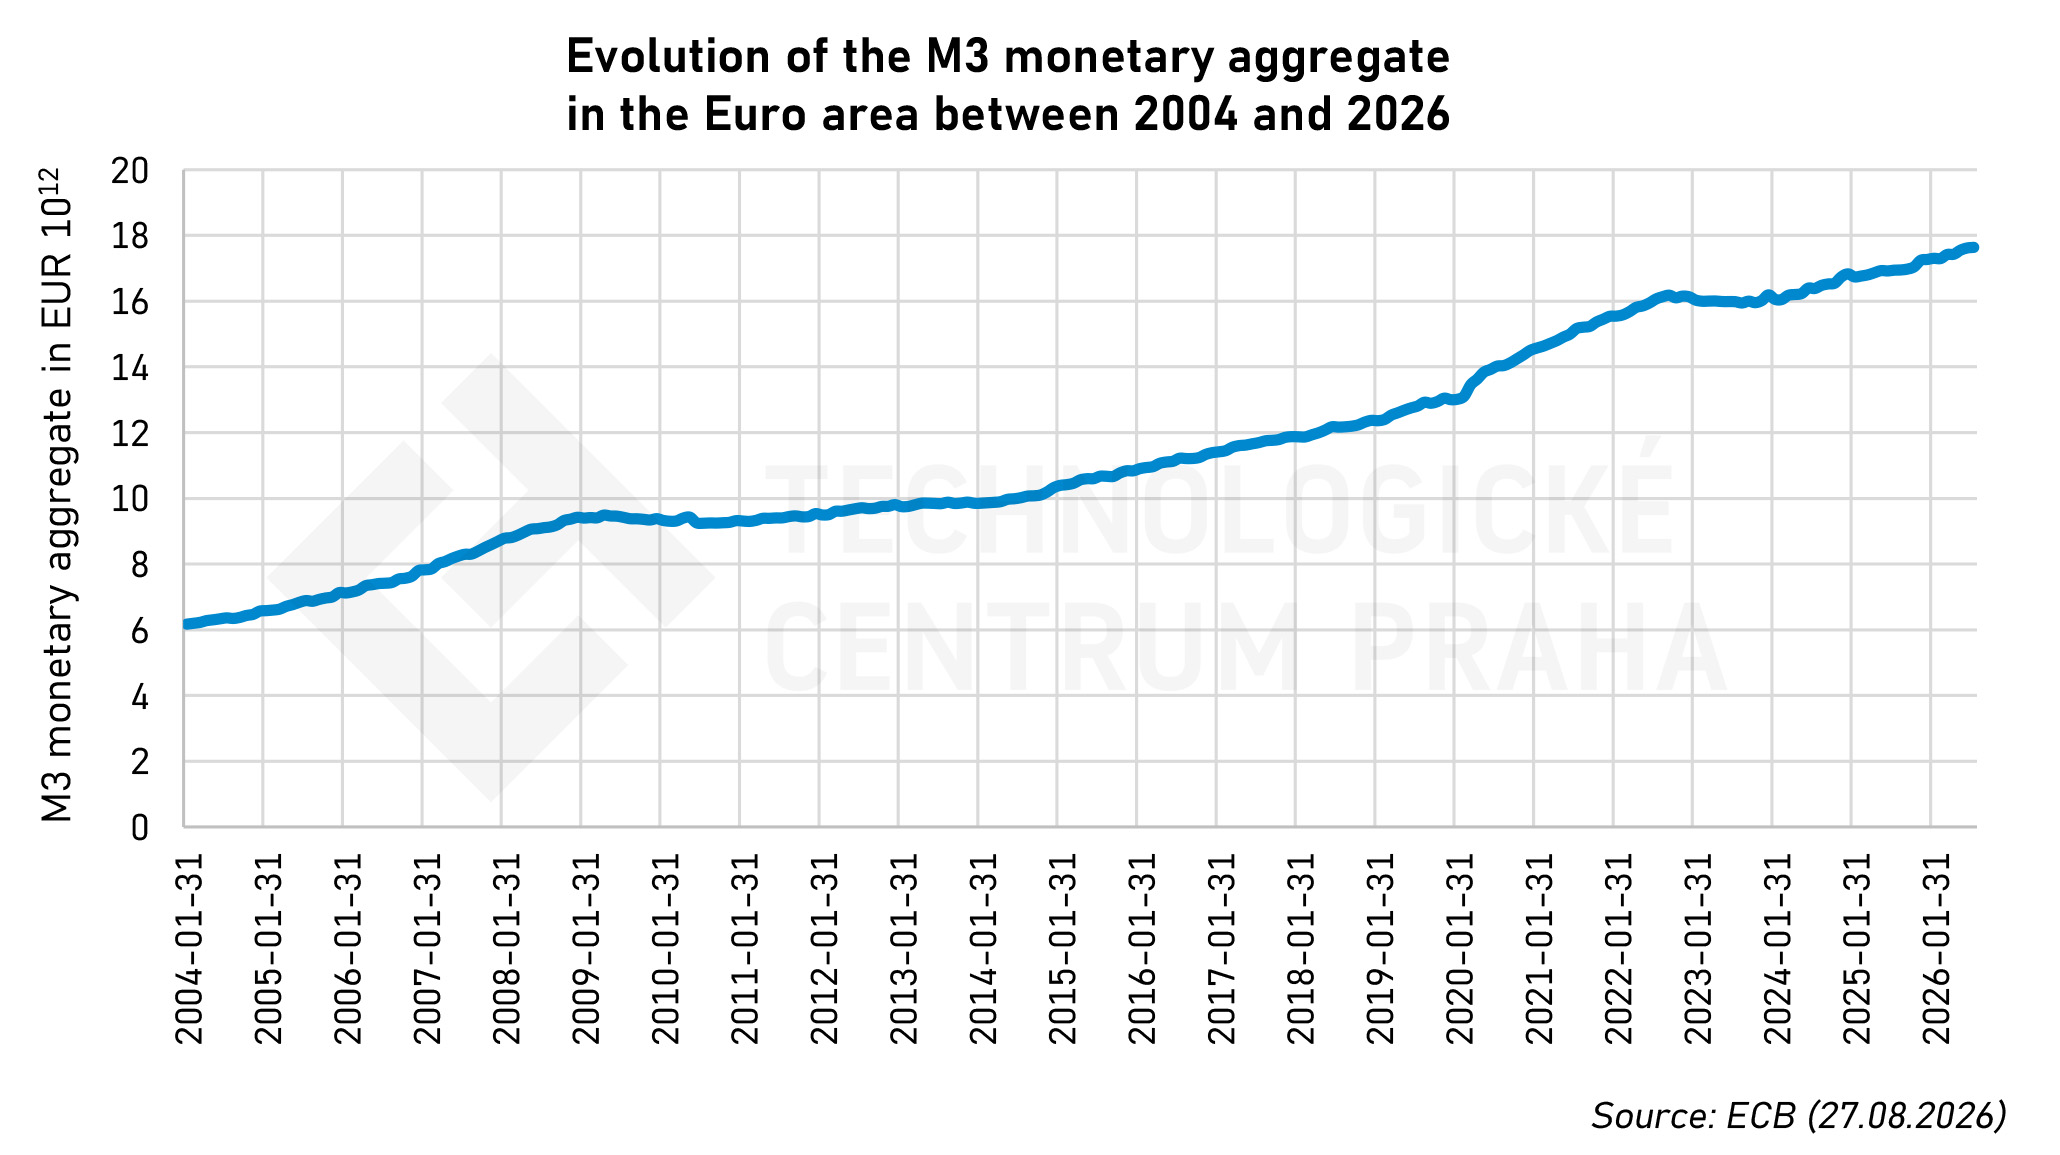
But what do those €200 billion mean in relation to previous Framework Programmes? To answer this question, let us look at the development of the money supply in the so-called Euro area. The total volume of broad money supply (i.e. currency in circulation, overnight deposits, term deposits and marketable instruments) is represented by the M3 monetary aggregate. According to data from the European Central Bank, its value in June 2026 stood at €17.6 trillion (i.e. 1012). In other words this means, that there is a total of €17.6 trillion present in the Euro area economy currently. However, in January 2007, i.e. at the start of the 7th Framework Programme, there was only €7.8 trillion present in the Euro area. This implies an average year-on-year growth rate in the broad money supply (over the period 31 January 2007 – 31 January 2026) of 4.3 per cent. (Compare this with the average year-on-year rate of real gross domestic product growth, which stood at 1.5 per cent in the Euro area over the last ten years.) Over the course of the three EU Framework Programmes for research and innovation – that is, over 20 years – the amount of money present in the Euro area economy has more than doubled. (See the figures below.)
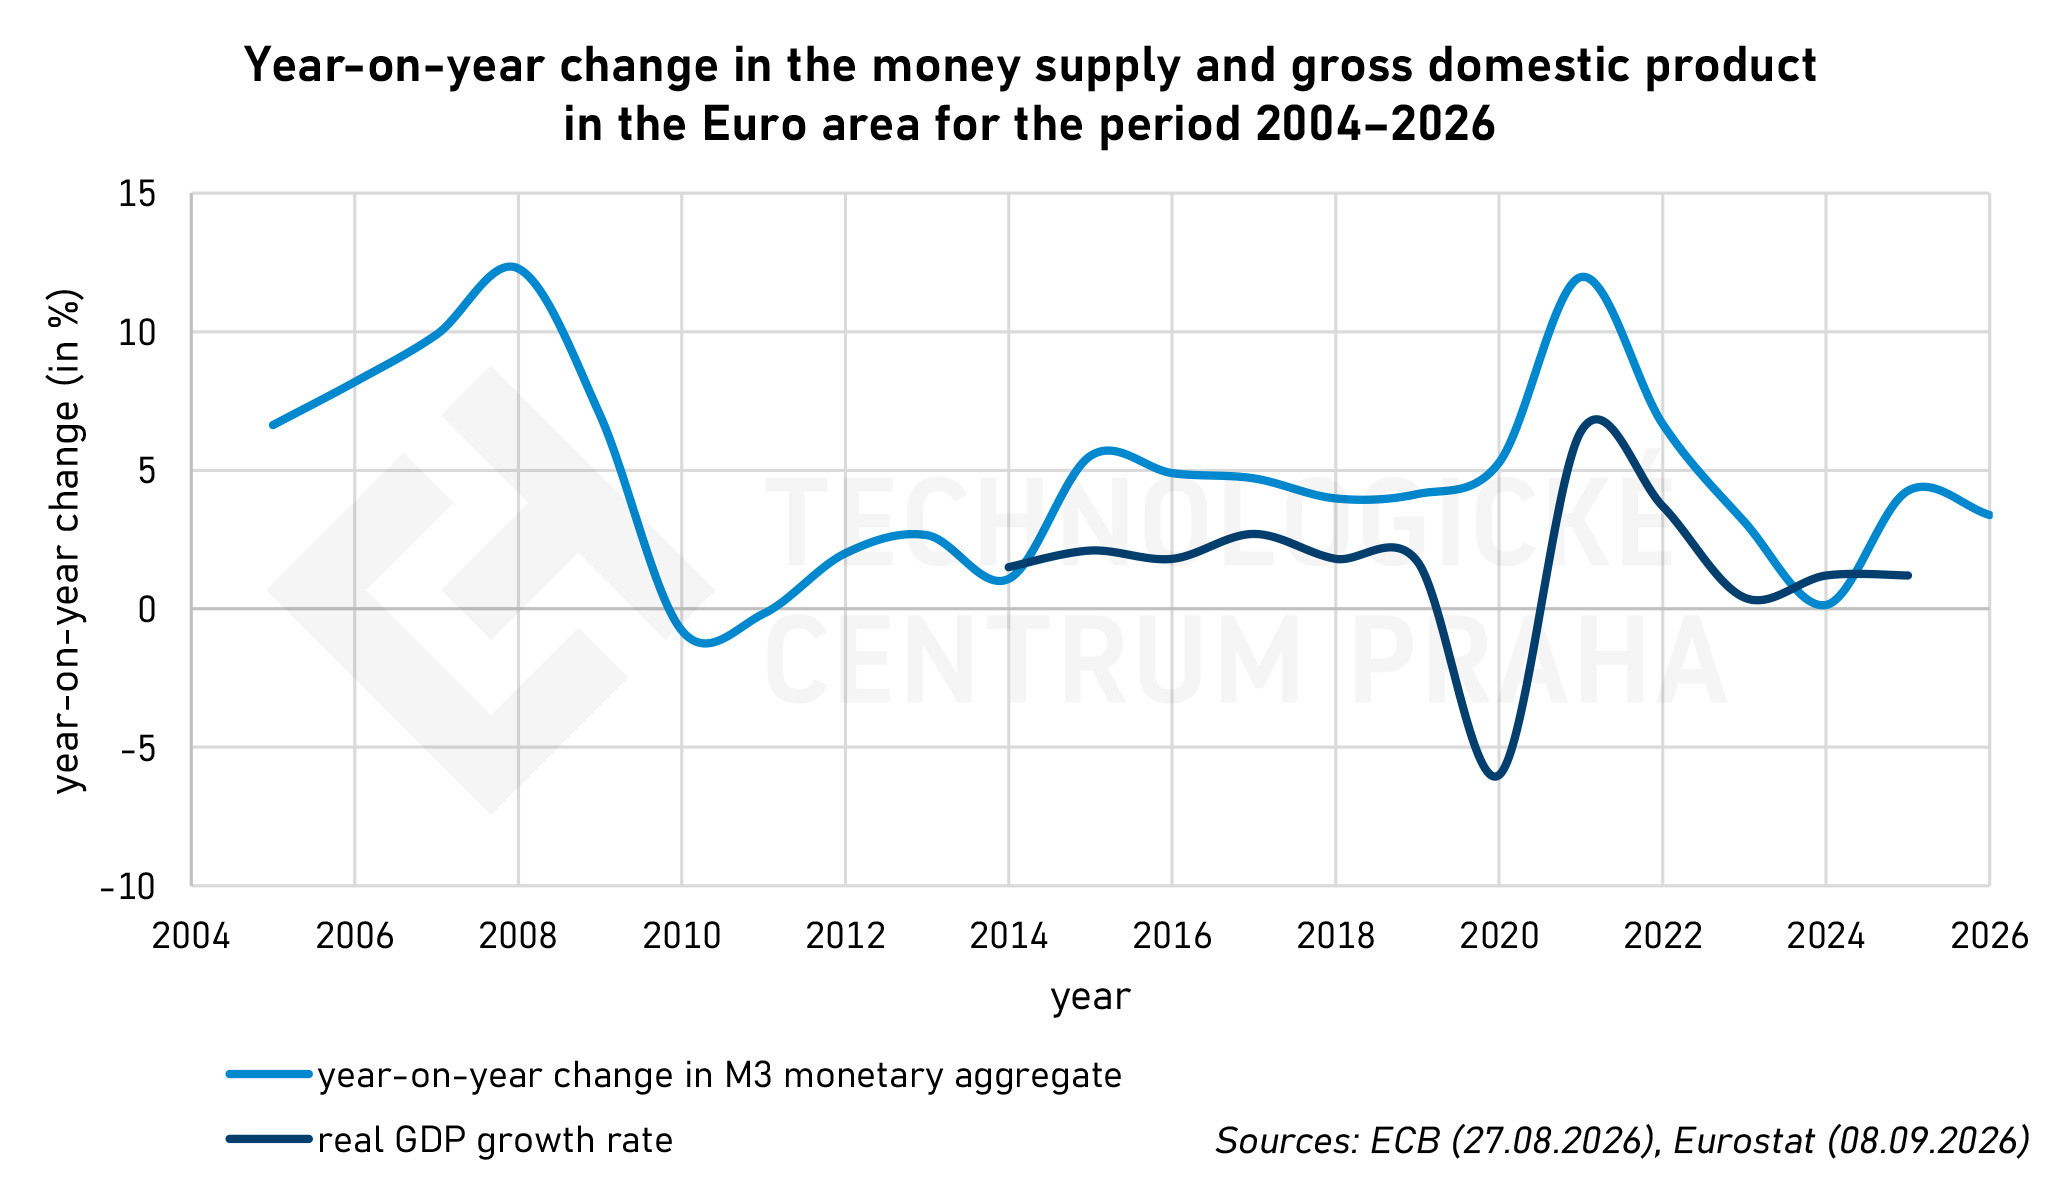
At this point, the reader may raise an objection to the methodology of this article, asking why we do not simply use the Consumer Price Index. The Consumer Price Index primarily reflects the rise in prices of consumer goods and services purchased by ordinary households; however, it does not consider the total amount of money in the economy. Yet the money present in the economy is not necessarily spent on consumer goods and services, but may end up in capital or property markets, thereby, amongst other things, driving up the prices of land, residential and commercial buildings in major cities, as well as construction work and building materials (and these goods and activities have a profound impact on the research, development and innovation sectors, as well as on the professional and personal lives of researchers). This is precisely why we use the M3 monetary aggregate as a broader measure of changes in the monetary environment, which, in addition to consumer price trends, also considers trends in asset prices, property prices and costs relevant to research – it reflects so-called selective inflation.
If, therefore, we use the M3 monetary aggregate as a rough benchmark, then for the same volume of goods and services that cost €9 in 2007, we now pay €20. Even the budgets of the EU’s Framework Programmes for research and innovation cannot escape this reality. Although, in nominal terms, the budget for the 7th Framework Programme was €50.5 billion, that for the subsequent Horizon 2020 programme was €77 billion and that for the current Horizon Europe programme is €95.5 billion, in real terms these amounts could buy roughly the same quantity of goods and services, as shown in the table below.
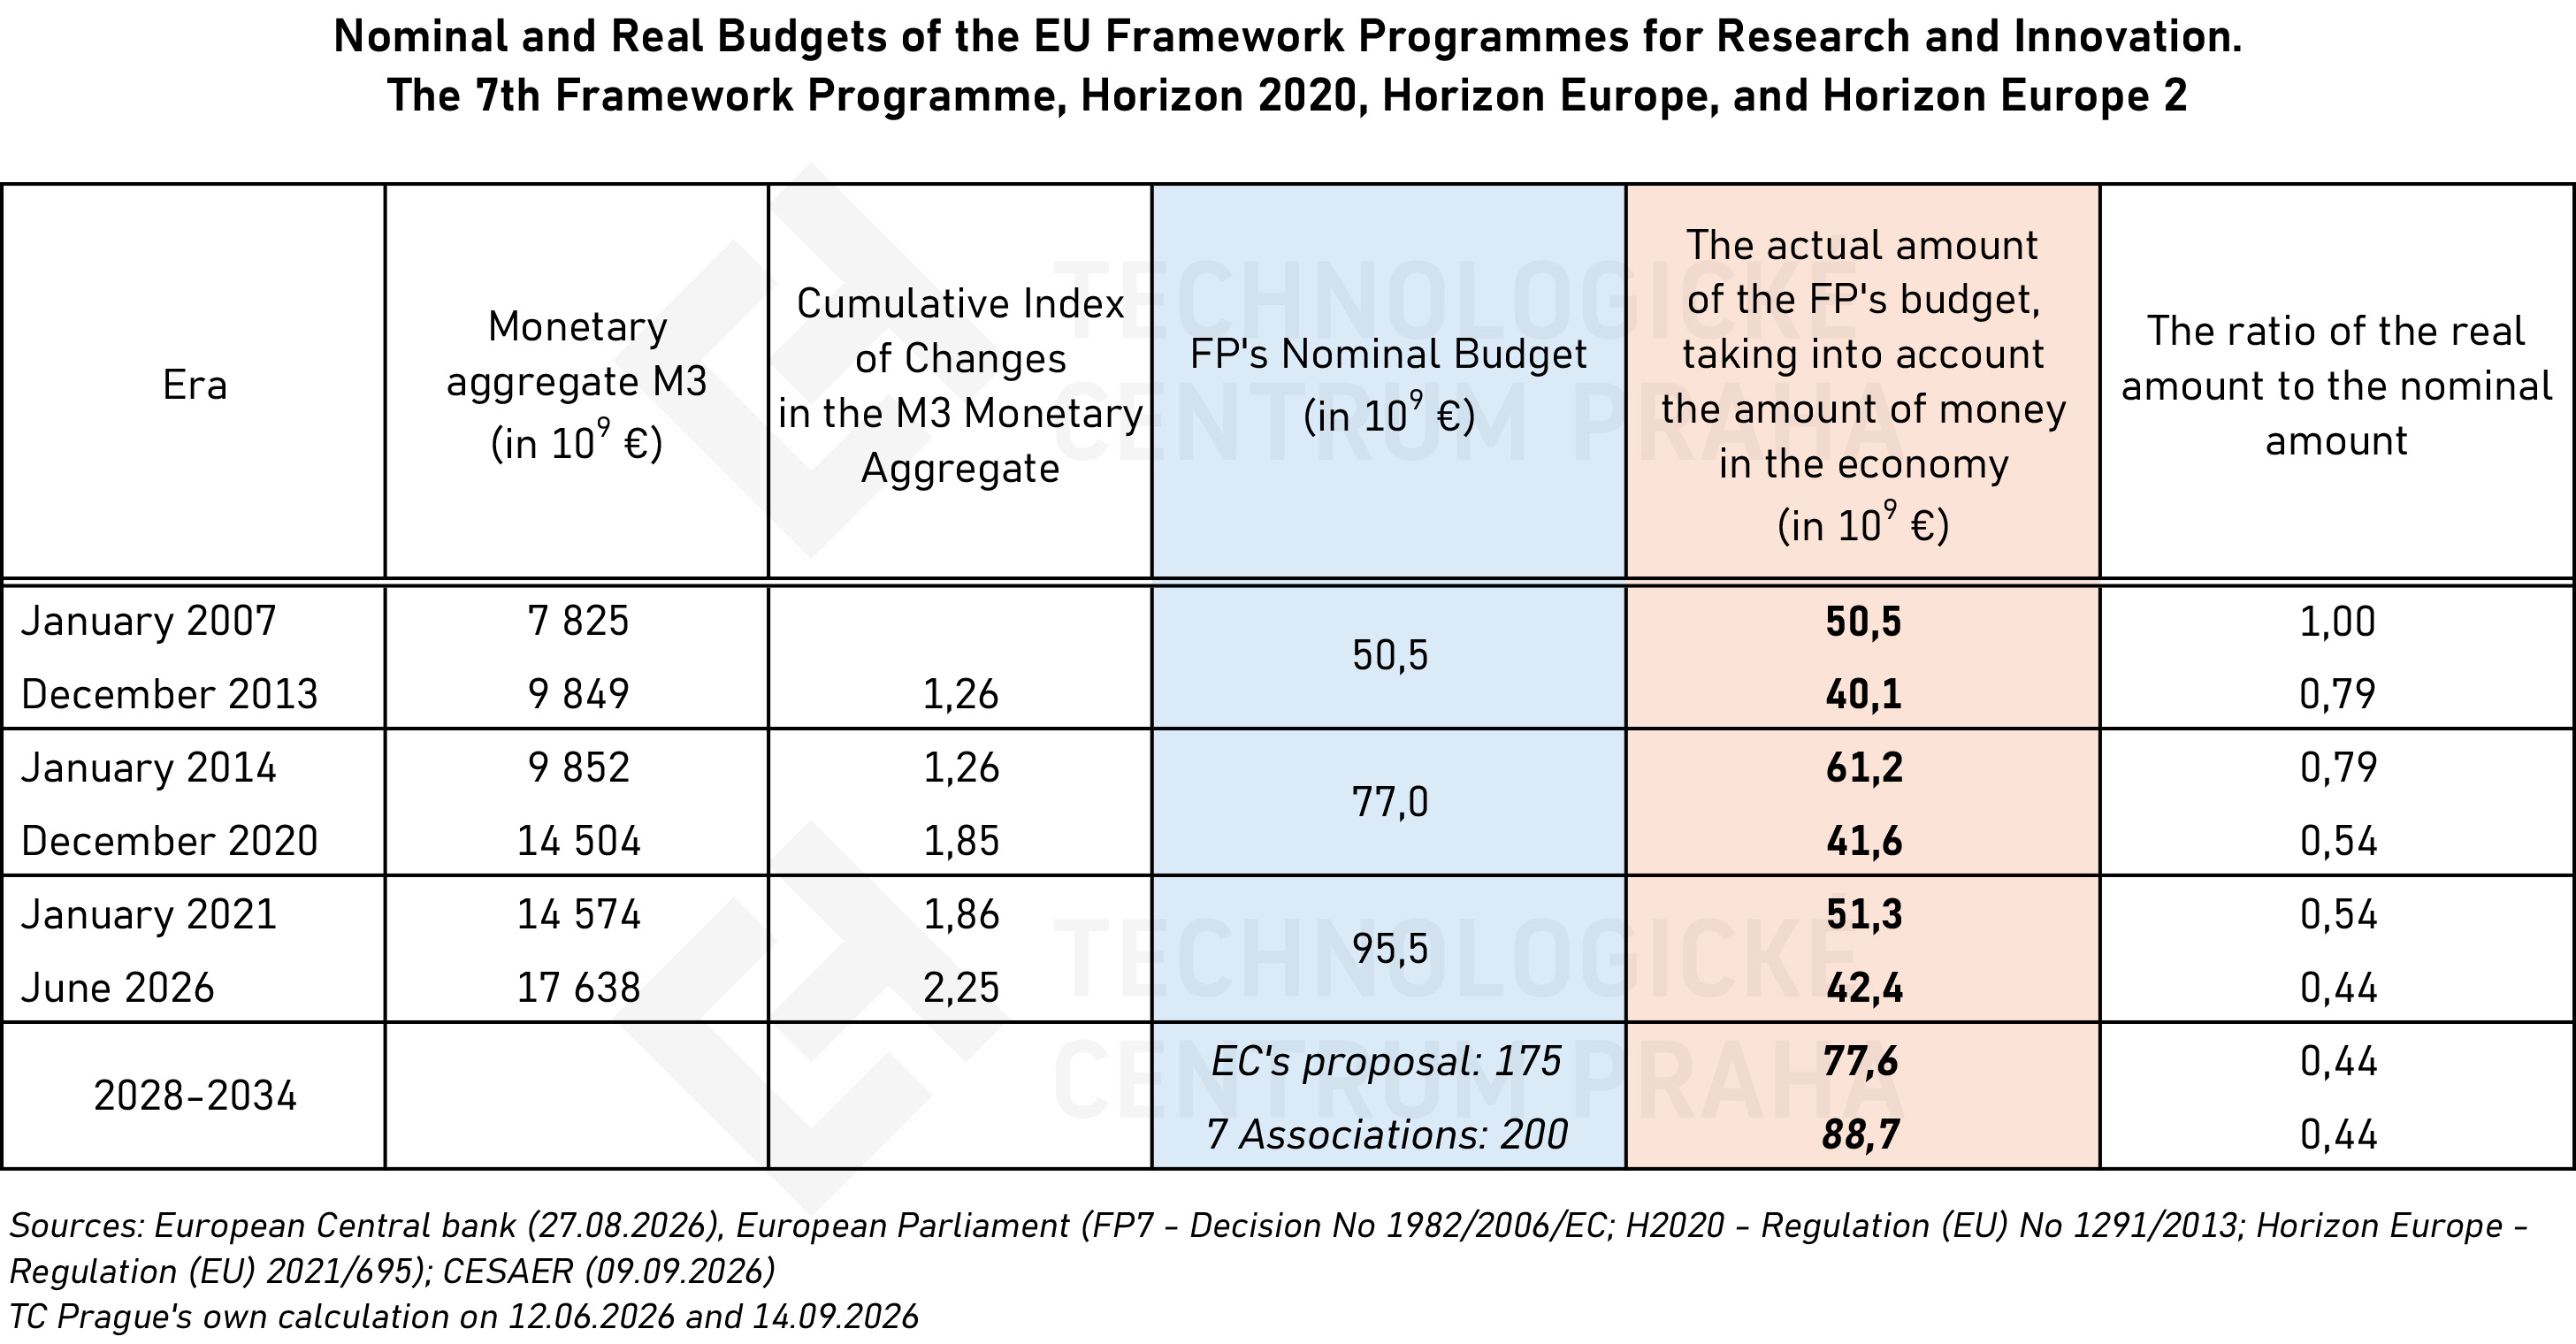
The budget for the 10th Framework Programme proposed by the European Commission, amounting to €175 billion (and the increase to €200 billion advocated by seven associations), appears at first glance to be very ambitious. In nominal terms, it is three to four times the size of the 7th Framework Programme, and 2.3 to 2.6 times that of the Horizon 2020 programme. Considering the long-term growth in the amount of money present in the economy, it is necessary to view these figures and ratios more objectively. In real terms, the proposed budget for the 10th Framework Programme is at most double that of the 7th Framework Programme and Horizon 2020. The proposed budget for the 10th Framework Programme also appears to be at most double that of Horizon Europe. However, given the current monetary expansion in the Euro area, it can be expected that by the end of 2034, the budget for the 10th Framework Programme will be, at most, 1.5 times higher than the budget for the current Horizon Europe programme in real terms.
Summary:
This article has shown that working with the money supply indicator is not merely an ‘academic exercise,’ but has a direct impact on the budgets of the EU’s Framework Programmes for research and innovation. The originally ambitious increases in the budgets of the Framework Programmes are gradually being eroded by the growth of the money supply in the Euro area. Its rapid expansion has the potential to cause serious debilitating effect to the European innovation and research ecosystem. This takes at least three forms.
1) Owing to the excessive growth of the money supply in the economy, calls are being made for nominally higher budgets for research, development and innovation activities. In reality, however, these budgets, whilst nominally higher, will be able to fund fewer research, development and innovation activities.
2) Although the preamble to Regulation (EU) 2021/695 of the European Parliament and of the Council, establishing the Horizon Europe Framework Programme for research and innovation, states that ‘the Programme should … attract talent at all levels and contribute to full engagement of the Union's talent pool…’, excessive growth in the money supply will lead to the exact opposite. Personnel costs account for roughly three-quarters of the costs of Framework Programme projects. The growth in the money supply and the resulting selective asset inflation will lead to a brain drain (as talented individuals will be unable to afford their own homes), either through emigration from the European Union or a shift to other sectors of the economy and other socio-economic activities that will be financially more attractive to them.
3) Selective inflation, manifested in rising prices of assets (property, building materials) and selected activities (construction work and skilled trades), will lead to a reduction in the construction development of universities and research institutions. This will subsequently be reflected in their reduced capacity for education, research, development and innovation.
Prepared by: Vladimír Vojtěch, vojtech@tc.cz, TC Prague, 15.09.2026